What Are Hong Kong Business Registration Rules on Reporting Changes?
Hong Kong businesses have one month to report key registration changes under the Business Registration Ordinance (Cap. 310). The Inland Revenue Department (IRD) administers these rules, and late notification can result in penalties or prosecution. For companies that incorporate in Hong Kong, this deadline is central to post-incorporation compliance. It applies for as long as the business operates. In this guide, we explain the seven updates that must be reported, their deadlines and the supporting documents required.
How Do You Report a Change of Business Name?
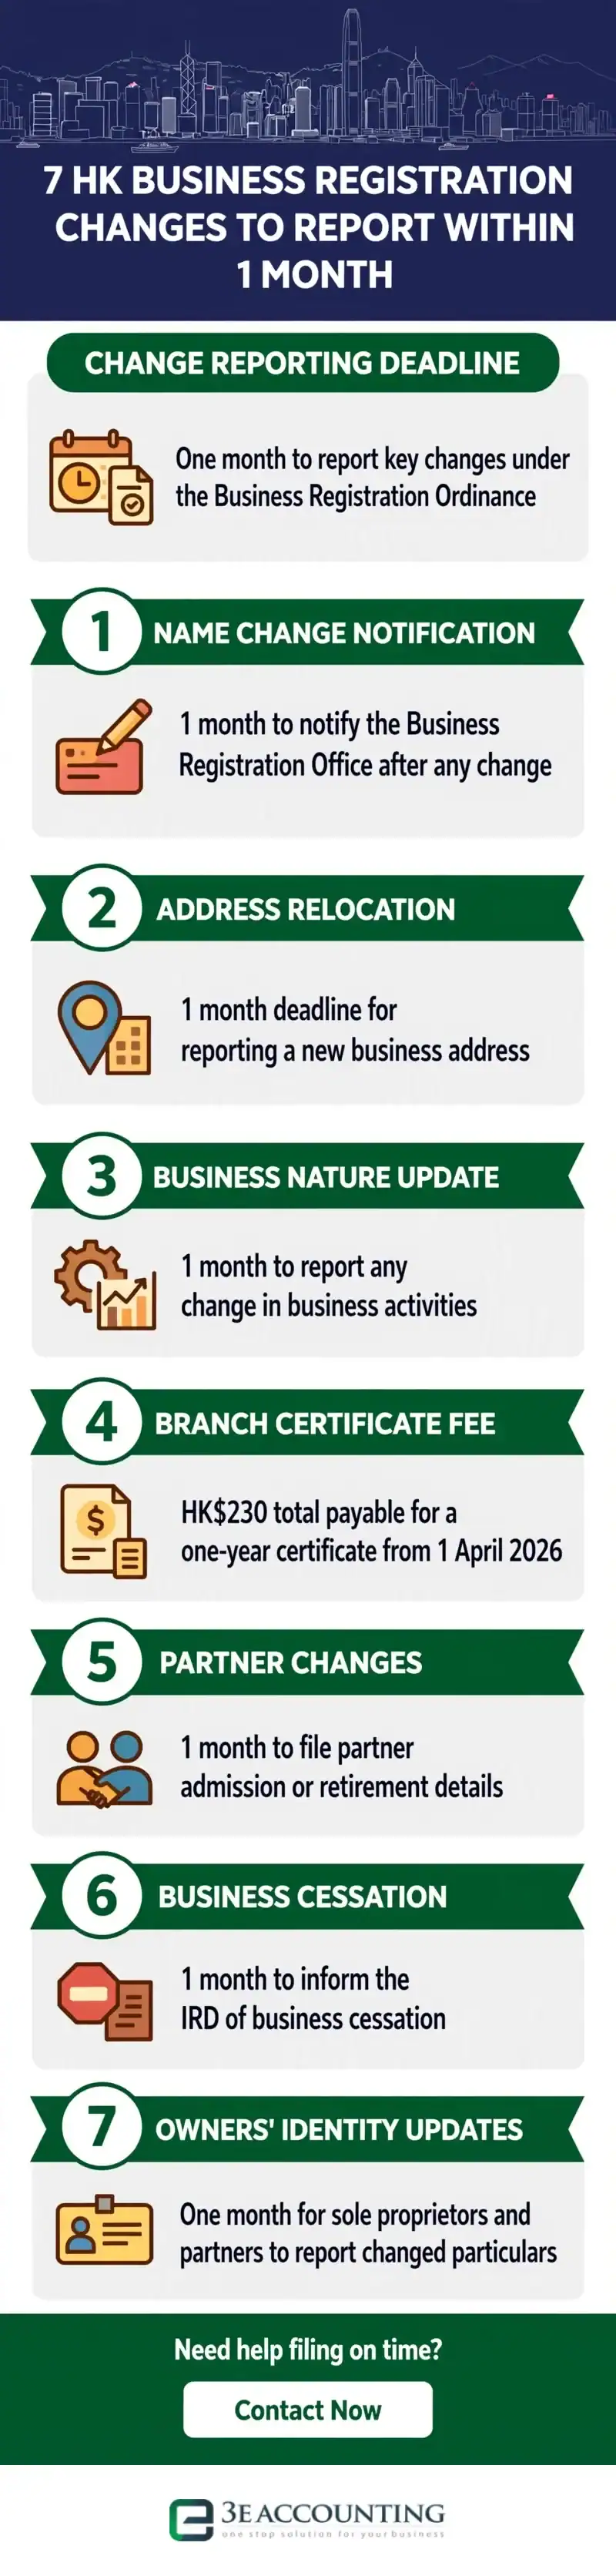
A change of business name must be notified to the Business Registration Office within 1 month; an additional business name is treated as a branch, while qualifying corporate-name changes are transmitted by the Companies Registry to the IRD. Notification may be submitted in writing, online via eTAX at GovHK or using Form IRC3111A. Before adopting a new name, a Hong Kong company name check confirms availability with the Companies Registry and avoids rejected filings.
How Do You Report a Business Address Relocation?
1 month is the deadline for reporting a business-address change after relocating. The Business Registration Office must be notified in writing or using Form IRC3111A, and may require address proof, such as a tenancy agreement or recent utility bill, for verification. Businesses that incorporate in Hong Kong should include this deadline in their post-incorporation compliance calendar. Both the principal place of business and the registered office address must stay current. Government correspondence, including renewal demand notes, is posted there. A change to a registered office also requires a separate Companies Registry filing. A missed demand note is no defence against late renewal penalties.
How Do You Report a Change in Business Nature?
1 month is the deadline for reporting any change in registered business activities to the Business Registration Office. This covers a modification of existing activities, an expansion into new lines, or a pivot to a different industry classification. The registered nature of business appears on the Business Registration Certificate. Outdated details can cause mismatches during bank account reviews, licence applications and Profits Tax assessments filed with the IRD.
Branch Registration Changes
From 1 April 2026 to 31 March 2027, a one-year branch registration certificate has a total payable amount of HK$230, comprising an HK$80 registration fee and an HK$150 levy. Every branch a company opens requires its own registration. The Business Registration Office must be told of an establishment or closure within one month. A branch can have a different registered business name, as each additional business name is treated as a branch of the business. Fees and levies are reviewed annually, so confirm current amounts before filing.
Hong Kong Business Registration Changes: One-Month Reporting Summary
| Change | Deadline | Key requirement |
|---|---|---|
| Business name change | 1 month | Notify the Business Registration Office using Form IRC 3111A with supporting evidence. |
| Business address relocation | 1 month | Provide written notice and valid address proof. |
| Business nature update | 1 month | Report the revised registered business activities. |
| Branch establishment or closure | 1 month | Notify the Business Registration Office; each branch requires its own registration. |
| Partner admission or retirement | 1 month | State the exact effective date of the change. |
| Business cessation | 1 month | Inform the Inland Revenue Department and settle outstanding Profits Tax obligations. |
| Owners' identity particulars | 1 month | Submit updated particulars with supporting documents. |
Partner Admission or Retirement
1 month is the deadline for filing notice when a partner joins or leaves. The notification must specify the exact date the restructuring took effect, so partnership records stay accurate. Where an admission or retirement changes the ownership structure, banks, landlords and counterparties may request evidence of the update before processing contracts. Late filings leave the register showing partners who have exited, exposing the business to disputes.
Cessation of Business Operations
From 1 April 2026 to 31 March 2027, a one-year business registration certificate has a total payable amount of HK$2,350, comprising an HK$2,200 registration fee and an HK$150 levy. Businesses that cease operations entirely must inform the Inland Revenue Department within one month. This allows tax records to be settled and closure to be finalised. Timely notification stops unnecessary renewal demands from being raised. Outstanding Profits Tax obligations must still be discharged before the business is wound down.
Owners' Identity Particulars
Sole proprietors and partners have one month to report changes to their identity particulars. This covers a change of legal name, revised identity details, or a new residential address. When corresponding with the Inland Revenue Department about owner updates, businesses should provide their tax identification number. Because the Inland Revenue Department matches each business to its owners for tax purposes, outdated particulars can delay correspondence and trigger compliance queries. Supporting documents, such as an updated identity document, should accompany the notification.
Ready to Keep Your Business Registration Current?
3E Accounting Hong Kong handles change notifications, renewals and full post-incorporation compliance filings for companies of every size.
Frequently Asked Questions
Under the Business Registration Ordinance (Cap. 310), failure to notify the Business Registration Office within one month of a change may result in penalties or prosecution. Filing promptly keeps the register accurate and avoids enforcement action by the Inland Revenue Department.
Form IRC 3111A is used to notify the Inland Revenue Department of changes in business particulars, such as a business name or address change. Supporting documents, such as address proof or an updated certificate, should be attached to the filing.
For certificates commencing between 1 April 2025 and 31 March 2026, a one-year branch certificate has a total payable of HK$230 (HK$80 registration fee plus the HK$150 levy), while the three-year branch registration fee is HK$508 before levy. For certificates commencing between 1 April 2026 and 31 March 2027, the one-year total payable is HK$230 (HK$80 registration fee plus HK$150 levy). Fees are reviewed annually, so confirm the current amounts with the IRD before filing.
Yes. A business that ceases operations entirely must inform the Inland Revenue Department within one month of cessation so tax records can be settled. Outstanding Profits Tax obligations must still be discharged before the closure is finalised.
Yes. As a Corporate Services Provider, 3E Accounting Hong Kong prepares and submits change notifications, branch registrations and renewals, and manages the wider post-incorporation compliance calendar so deadlines are never missed.
Abigail Yu
Director
Abigail Yu oversees executive leadership at 3E Accounting Group, leading operations, IT solutions, public relations, and digital marketing to drive business success. She holds an honors degree in Communication and New Media from the National University of Singapore and is highly skilled in crisis management, financial communication, and corporate communications.