How Do Hong Kong Employer Tax Forms Work?
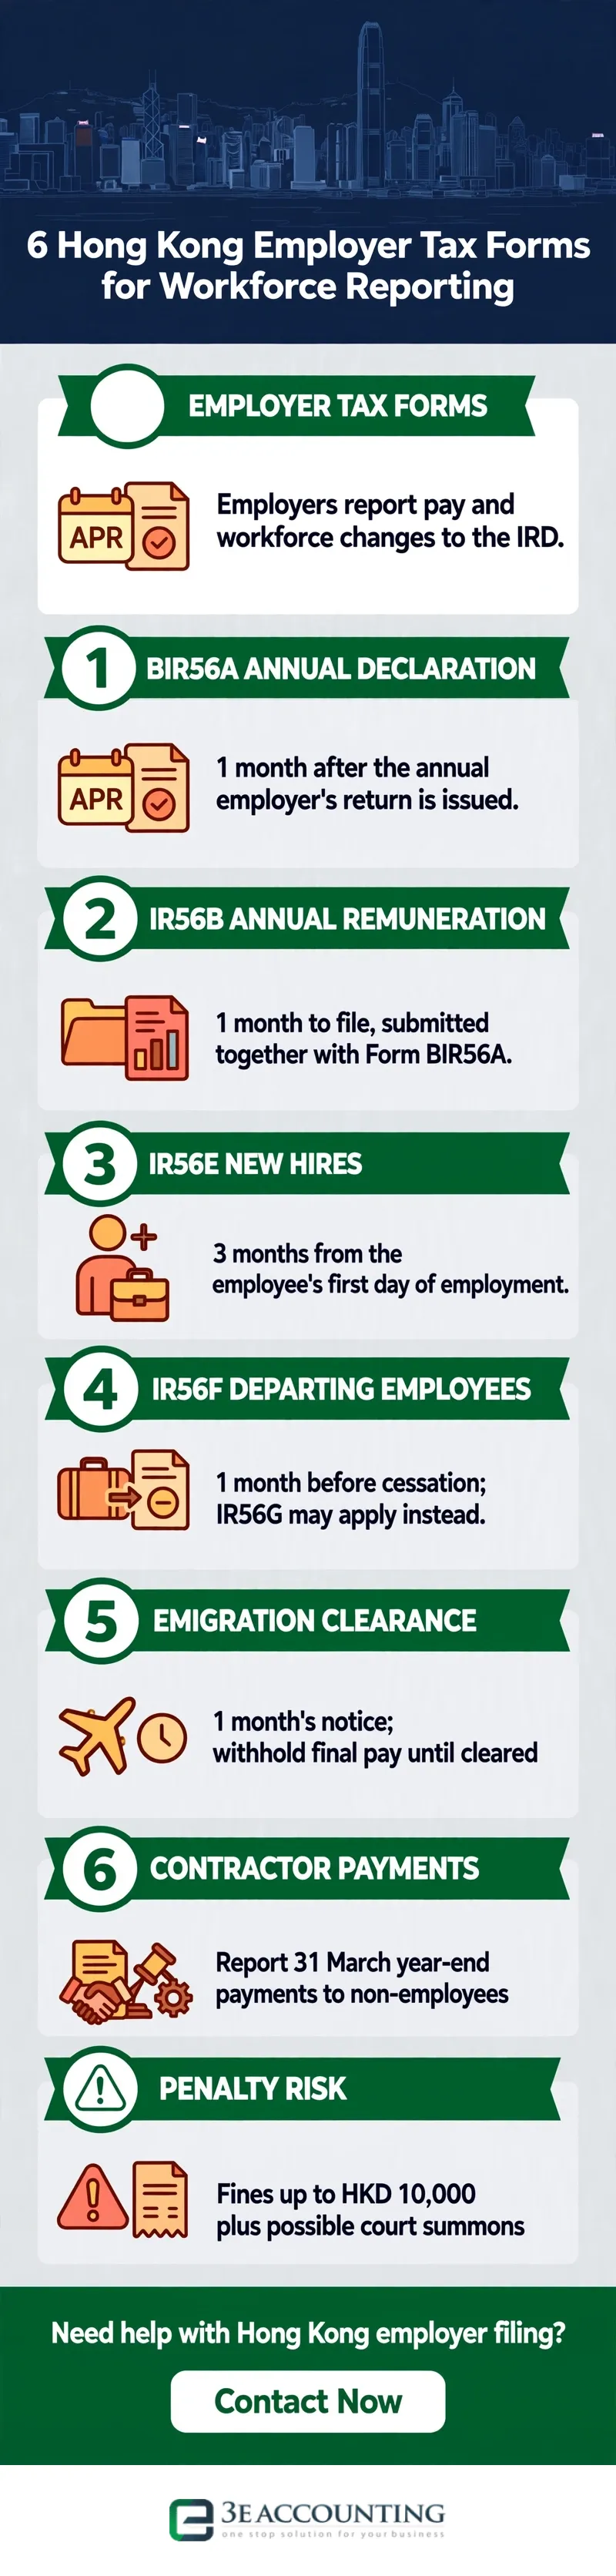
Hong Kong employers use tax forms to report remuneration and workforce changes to the Inland Revenue Department (IRD). Getting them right helps avoid queries, employee disputes and penalties. In this infographic, we explain six employer returns, their deadlines and common filing pitfalls.
Most obligations follow the routine BIR56A and IR56B cycle each April. New hires, departures and emigration trigger separate forms and deadlines. Newly incorporated companies may have reporting duties when they hire their first employee, depending on the circumstances and applicable deadlines. We help clients across Hong Kong build filing calendars that keep workforce reporting on schedule year-round.
What Is Form BIR56A Annual Declaration?
Form BIR56A must reach the IRD within 1 month of the employer's annual return being issued. It acts as the master declaration for the year ended 31 March. It identifies whether employees are reportable and records the number of IR56B forms submitted. The detailed IR56B and IR56M forms are filed alongside it, anchoring the annual reporting cycle. Form IR6036B is the covering declaration for IR56M.
What Is Form IR56B Annual Remuneration?
Form IR56B is due within 1 month of the annual employer's return being issued, filed with BIR56A. It reports salary, wages, leave pay, commissions, bonuses and allowances for reportable employees. Report gross income before employee Mandatory Provident Fund (MPF) deductions; employer MPF contributions are not reported as income. Not every employee requires a form, so check the IRD's reporting criteria. Give each reported employee a copy. Accurate entries matter because the IRD matches them against individual Salaries Tax returns.
What Is Form IR56E for New Hires?
Form IR56E is due within 3 months of a new employee commencing employment. The IRD requires it for every hire — full-time, part-time or casual — whenever that person is likely to be chargeable to Salaries Tax. The form carries the employee's name, address, start date and expected remuneration. Late notification leaves the department without a payroll record and can delay the employee's first assessment.
Form IR56F for Departures
For an employee likely to be chargeable to Salaries Tax, file Form IR56F at least 1 month before cessation unless IR56G applies; the IRD may accept shorter notice. It reports cessation of employment, including death. If an employee dies, advance notice is impossible; file promptly after the death. If the employee is also leaving Hong Kong, IR56G may be required instead. The report covers remuneration up to the cessation date. This gives the IRD time to assess the reported income. Employers who wait until exit week may miss this deadline.
Employer tax form reporting timeline
| Form | Reporting event | Filing timeline |
|---|---|---|
| BIR56A | Annual employer's declaration | Within 1 month of issue |
| IR56B | Annual employee remuneration | Within 1 month of BIR56A issue |
| IR56E | New employment | Within 3 months of commencement |
| IR56F | Cessation of employment | At least 1 month before cessation |
| IR56G | Departure from Hong Kong | At least 1 month before expected departure |
| IR56M | Reportable non-employee payments | Submit with IR6036B alongside BIR56A |
Form IR56G for Emigrating Staff
File Form IR56G at least 1 month before an employee chargeable to Salaries Tax leaves Hong Kong for more than 1 month, unless the employee is required to leave frequently in the course of employment. Employers must withhold payments for 1 month from filing or until the IRD issues a letter of release, whichever is earlier. Paying out early can leave the business exposed to that employee's outstanding Salaries Tax, so finance teams build the hold into every relocation.
Form IR56M for Contractors
Form IR56M reports payments made to non-employees for the year ended 31 March. It covers reportable payments to local, non-incorporated service providers, including consultants and sub-contractors. Reporting thresholds depend on the type of service. Submit IR56M with Form IR6036B alongside BIR56A. This extends reporting beyond payroll to qualifying contractor payments.
Penalties for Filing Non-Compliance
An incorrect return made without reasonable excuse can attract a fine of HKD 10,000 plus a further fine of up to three times the tax undercharged. The Inland Revenue Ordinance treats every IR56 form as a statutory duty, and the IRD may add court summons for persistent non-compliance. For practical guidance on running business in Hong Kong, employers should calendar each trigger — hires, departures, emigration and the April annual cycle. One missed deadline can lead to further IRD review and higher penalties.
Need Support With Employer's Returns?
Our Hong Kong team keeps your IR56 filings accurate, on time and penalty-free.
Frequently Asked Questions
Within 3 months of a new employee commencing employment, whether full-time, part-time or casual, provided that person is likely to be chargeable to Salaries Tax.
Form IR56F reports cessation of employment, generally at least 1 month beforehand; after an employee's death, file promptly. Form IR56G reports an employee's departure from Hong Kong for good or a substantial period. Withhold payments for 1 month from filing IR56G or until the IRD issues a letter of release, whichever is earlier.
The Inland Revenue Department normally issues BIR56A in early April. BIR56A and IR56B are due within 1 month of issue. Submit IR56M with IR6036B alongside BIR56A for reportable payments in the year ended 31 March.
Generally, no. IR56M covers reportable payments to local, non-incorporated service providers, such as sole-proprietor consultants and sub-contractors. Different reporting rules may apply to certain service company arrangements.
Late employer filings and inaccurate returns without reasonable excuse can lead to a fine of HKD 10,000, with a further tax-based fine possible. For an inaccurate return, the further fine can be up to three times the tax undercharged; it can also apply to some late returns. The IRD may pursue prosecution for non-compliance.
Abigail Yu
Director
Abigail Yu oversees executive leadership at 3E Accounting Group, leading operations, IT solutions, public relations, and digital marketing to drive business success. She holds an honors degree in Communication and New Media from the National University of Singapore and is highly skilled in crisis management, financial communication, and corporate communications.