Why Do eTAX Filing Extensions Matter in Hong Kong?
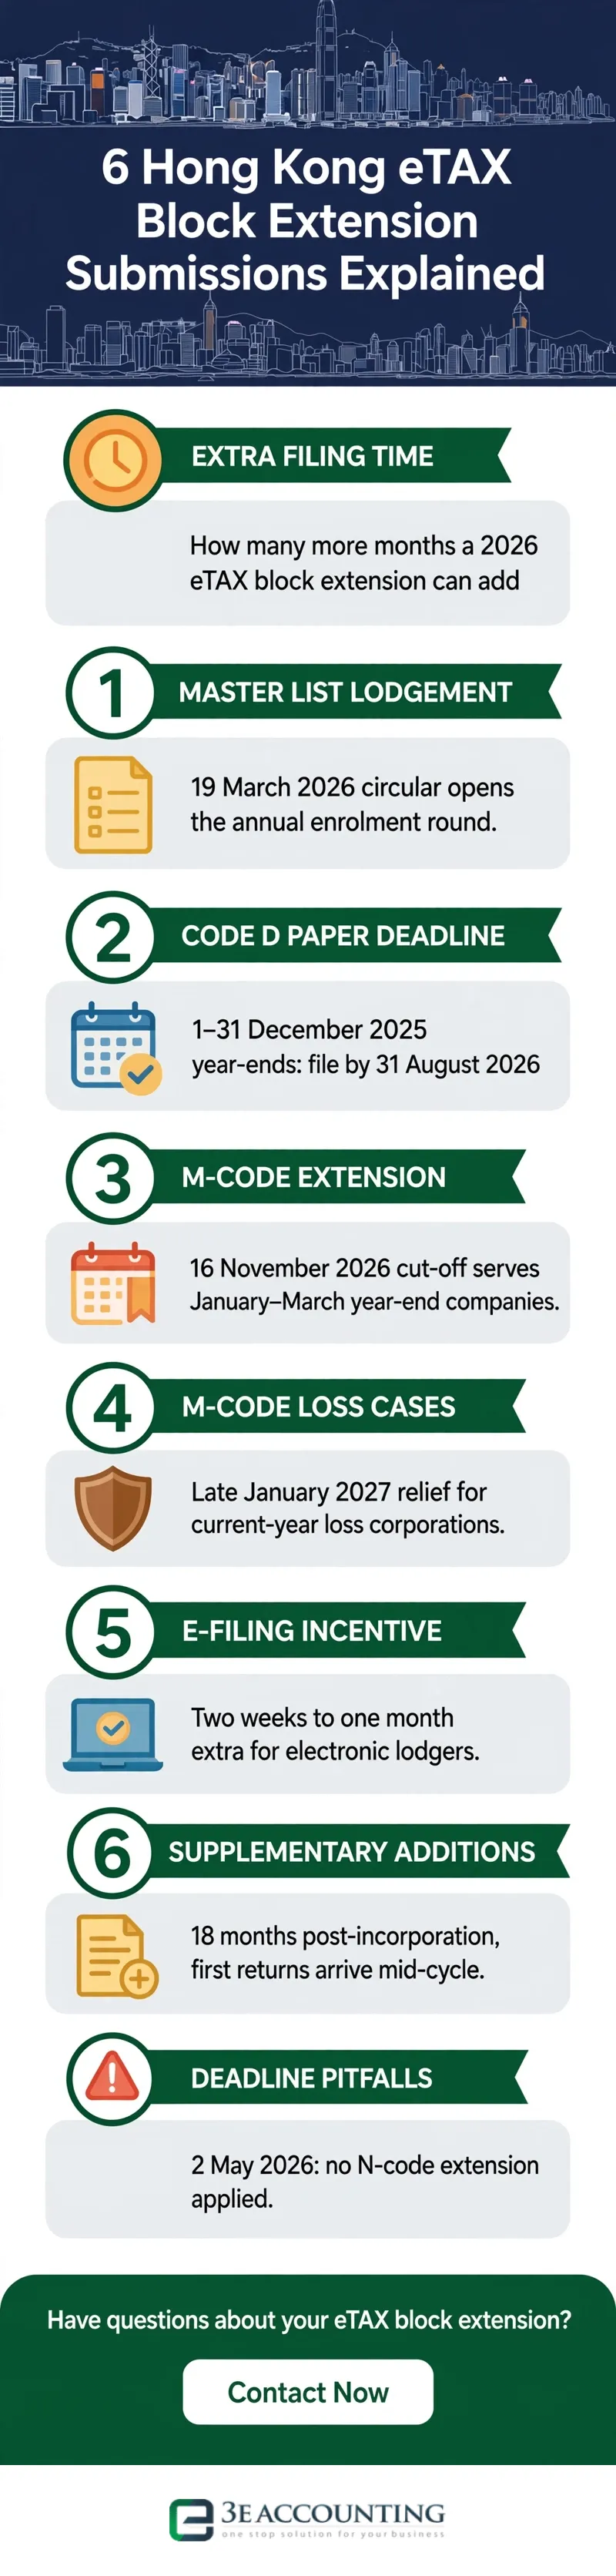
How much extra time can a Hong Kong eTAX block extension add to your 2026 Profits Tax Return filing deadlines? In this infographic, we walk through six filing considerations: client notifications, deadline categories and incentives. Our Hong Kong team stands ready if you would rather get in touch. Each spring, the Inland Revenue Department (IRD) issues Profits Tax Returns to active corporations, generally with a one-month filing period. Eligible represented clients may receive more time under the block extension scheme. Missing an applicable notification or application deadline can affect the extension available. For the wider compliance calendar, see our Hong Kong financial year-end checklist. Understanding these requirements can help SMEs and multinationals reduce the risk of late-filing penalties.
How Are Initial Master Client List Changes Lodged?
The IRD issued its Circular Letter to Tax Representatives on the 2025/26 Block Extension Scheme on 19 March 2026. Representatives did not need to reapply for clients already notified to the IRD before 20 February 2026 where details had not changed. They needed to notify the IRD of new clients, ceased representations and accounting-date changes by the applicable deadlines. From April 2026, block extension applications and notifications must be submitted through the Tax Representative Portal.
What Is the Accounting Code 'D' Extension Deadline?
Represented D-code cases with 1–31 December 2025 year-ends had until 31 August 2026 to file on paper, or 2 October 2026 for qualifying electronic filings. This eTAX block submission defers the Profits Tax Return deadline more than three months beyond the standard May cut-off. December year-ends align with audit cycles, so the extended window lets accounts and computations finish before lodgement. Lodging the block list confirms each client's category, keeping late-summer filing valid rather than penalised.
What Is the Accounting Code 'M' Standard Deadline?
For represented M-code cases with 1 January–31 March 2026 year-ends, the paper-filing deadline is 30 November 2026. The IRD's 20 October 2026 supplementary circular moved it from 16 November and extended the electronic-filing deadline to 30 December 2026. M code is a deadline category rather than a separate submission; additional conditions apply to electronic filing and loss-case extensions.
Code 'M' Loss Cases Submission
Qualifying M-code loss cases may apply for a further extension to 1 February 2027. Under the IRD's 19 March 2026 circular, a list of cases must be received by 2 November 2026; exceptionally, individual requests may be lodged by 16 November 2026. The return must show an allowable current-year loss. Electronic filing does not extend the loss-case deadline beyond 1 February 2027.
Block extension filing considerations
| Item | Purpose or category |
|---|---|
| Client list | Notify the IRD of represented clients and relevant changes |
| D code | December year-end deadline category |
| M code | January–March year-end deadline category |
| M-code loss cases | Further relief for an allowable current-year loss |
| Electronic filing | A further extension may be available |
| Supplementary additions | Notify the IRD of newly appointed clients |
Electronic Lodgement Incentive Extension Submission
The IRD's 19 March 2026 circular provides a further one-month extension for qualifying electronic filings. For voluntary e-filing, the application must reach the IRD at least seven working days before the return is otherwise due, and the return must be filed electronically through the Business Tax Portal. Certain mandatory e-filers receive the extension automatically if they notified the IRD of their status before March 2026; others must apply. The M-code loss-case deadline is not extended further for electronic filing.
Supplementary Client Addition Block Submission
First Profits Tax Returns arrive roughly 18 months after incorporation. A newly incorporated Hong Kong company generally receives its first Profits Tax Return about 18 months after incorporation, potentially outside the April bulk issue. Representatives notify the IRD of new clients through the Tax Representative Portal; first Profits Tax Returns issued during the year generally have a three-month filing period without an extension application.
Critical Filing Deadlines and Pitfalls
N-code cases received no ordinary Hong Kong eTAX block extension; for returns issued in the April 2026 bulk issue, the paper-filing deadline was 4 May 2026. A further extension for eligible electronic filing could be available. Missing an applicable deadline can affect the extension and expose the corporation to estimated assessments or penalties under the Inland Revenue Ordinance. Aligning each client's category with its year-end helps manage filing compliance.
Need Help With Your IRD Block Extension Submission?
Our Hong Kong team manages eTAX lodgements, deadlines and Profits Tax Return filings end to end.
Frequently Asked Questions
It is the IRD's arrangement for extending eligible represented clients' Profits Tax Return deadlines. For the 2025/26 cycle, the paper-filing deadlines for qualifying D-code and M-code cases were extended to 31 August and 30 November 2026 respectively.
N-code cases, meaning corporations with accounting year-ends from 1 April to 30 November 2025, received no ordinary block extension. For returns issued in the April 2026 bulk issue, the paper-filing deadline was 4 May 2026; an electronic-filing extension could be available if applicable conditions were met.
Eligible represented M-code cases with an allowable current-year loss can apply for an extension to 1 February 2027. The IRD must receive a list by 2 November 2026; exceptionally, individual requests may be lodged by 16 November 2026.
Qualifying electronic filings may receive a further month. Voluntary e-filers must apply at least seven working days before the return is otherwise due; the M-code loss-case deadline is not extended further for e-filing.
Representatives should notify the IRD of newly appointed clients as required. First Profits Tax Returns generally arrive about 18 months after incorporation and are due three months after issue, without an extension application.
Abigail Yu
Director
Abigail Yu oversees executive leadership at 3E Accounting Group, leading operations, IT solutions, public relations, and digital marketing to drive business success. She holds an honors degree in Communication and New Media from the National University of Singapore and is highly skilled in crisis management, financial communication, and corporate communications.